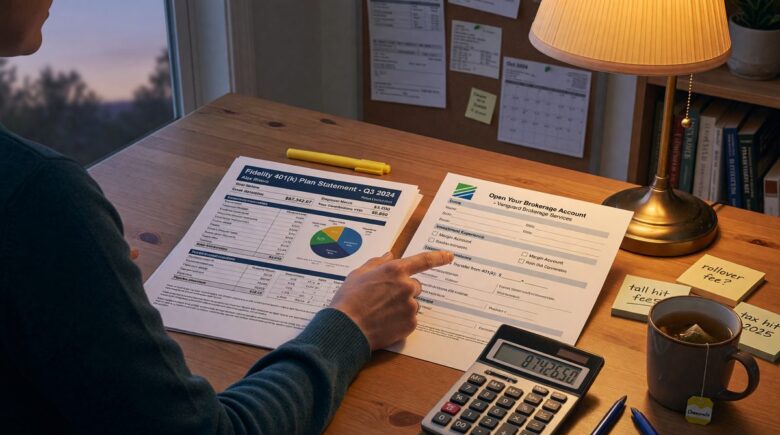
Max Out Your 401(k) or Open a Taxable Brokerage Account? Here’s the Answer
Maxing your 401(k) beats a taxable brokerage account for most workers—especially if you earn middle-class income or above. Here's when to break the rule.
Maxing your 401(k) beats a taxable brokerage account for most workers—especially if you earn middle-class income or above. Here's when to break the rule.
Both track the same benchmarks with nearly identical returns, but ETFs edge ahead on taxes while index funds win on simplicity. See which fits your investing style.
Build a bond ladder with staggered maturities to collect regular income and reduce reinvestment risk—no rate forecasting needed.
71% of gig workers already own retirement assets. Here’s how to build a freelancer investment portfolio through self-directed accounts that can match W-2 employee savings rates.
The S&P 500 averages 38% returns in the 12 months after a market bottom. Most investors should keep investing during a recession—unless your income is at risk or savings are...
Boost your emergency fund growth by 90% with a 4.5% HYSA and automated deposits. Learn how to avoid debt and save smarter in 2026.
Your tax bracket now versus retirement determines the winner. If you’re at 22% or below expecting rate hikes, Roth wins. At 32%+ dropping later, Traditional saves more.
Short-term capital gains tax can hit 37%—often because first-time investors skip goal-setting, ignore hidden fees, and let emotions drive trades. Here’s how to avoid them.
A $10,000 five-year CD ladder can generate $2,200 in interest versus $500 in savings. See how staggered maturity dates unlock better rates and annual access to your money.
A teacher earning $55K proved you can max out a Roth IRA by saving just $625/month—without a six-figure income. See what it actually takes.
Dividends have driven 40% of S&P 500 returns since 1930. Reinvestment plans automatically compound that growth—here’s how to set one up commission-free.
I bonds offer 4.26% through 2026 with full inflation protection, while Treasury bills yield 3.8-4.0% with better liquidity. Compare features and find which fits your savings goals.
Read More
Cut winter utility bills with smart energy-saving moves, weatherization tips, and assistance programs to keep your home warm and costs down.
Read More
A 24-year-old in Minneapolis grew $7,800 in 14 months using micro-investing and automatic rebalancing. Consistent automation and low fees drove the success.
Read More
A 25-year-old maxing a Roth IRA could accumulate $74,400 more after-tax wealth than a taxable brokerage account over 30 years. Here's why it matters.
Read More
Financial experts recommend 15-20% savings, but most Americans save just 4.6%. Find the right percentage based on your age, debt, and income stability.
Read More
A $287 average balance can lose 12.5% annually to fees alone. See which micro-investing apps actually grow small balances instead of eating them.
Read More